Supplier Early-Payment Discounts: Is Borrowing Worth the Saving?
Should you borrow to pay a supplier early? Compare the invoice discount with interest, fees and your minimum cash buffer using a practical worked example.
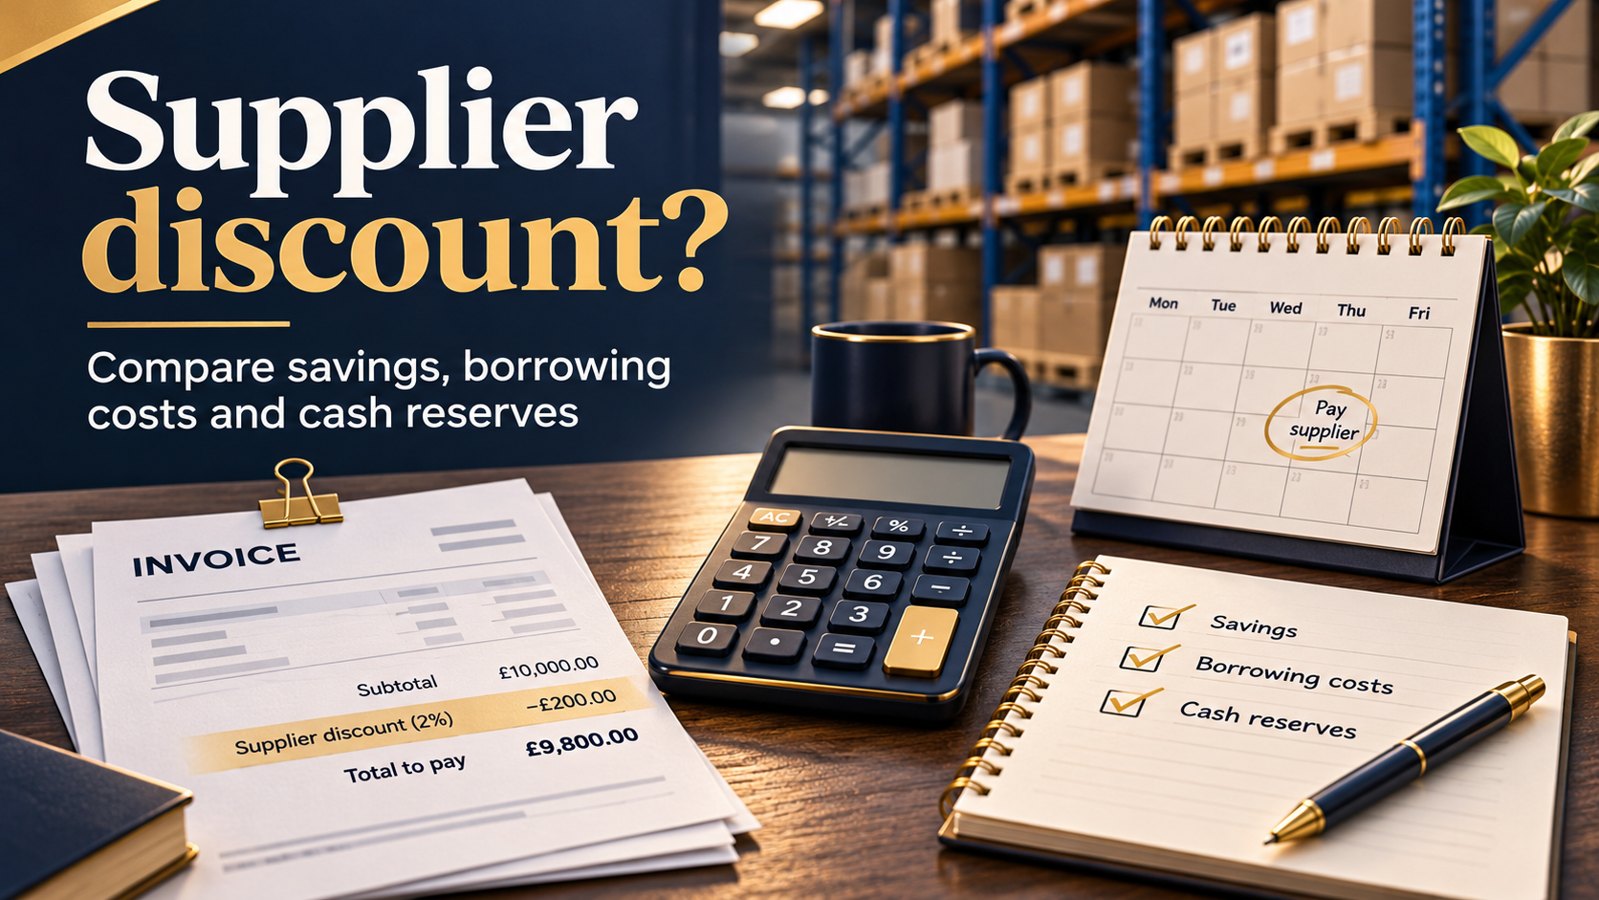
Borrowing to capture a supplier early-payment discount can make sense when the confirmed saving exceeds the additional interest and fees, repayment is credible, and enough liquidity remains for essential operations. Start with the dollar comparison for the actual payment dates. A discount that looks attractive as an annualized percentage can still be a poor choice if it consumes the cash or credit needed for payroll.
What does 2/10, net 30 mean?
These illustrative invoice terms mean a 2% discount for payment within 10 days, with the full invoice otherwise payable within 30 days. Paying on day 10 instead of day 30 brings cash outflow forward by 20 days. Confirm whether the clock starts at the invoice date, delivery or acceptance, and whether cleared funds must arrive by the deadline.
BDC explains that early-payment discounts should be assessed against financing costs, cash flow and alternative uses of money. Its guidance provides useful context; the calculations below are independent fictional examples, not available CGFS terms. Source: https://www.bdc.ca/en/articles-tools/money-finance/manage-finances/early-payment-discount-big-returns-business
Compare the saving with the incremental financing cost
Use this decision calculation: confirmed invoice discount minus additional borrowing interest minus additional fees equals the estimated net saving before tax. Compare two complete cash schedules: paying early and paying on the normal due date. Include costs that differ between the alternatives, and separately consider the full cost of any new facility required to make the strategy possible.
Illustration: a distributor owes $250,000 and can pay $245,000 on day 10 instead of $250,000 on day 30. The saving is $5,000. Assume it can draw $245,000 from an existing facility at a fictional 12% simple annual rate, repay on day 30 and incur a $250 transaction fee. Using a 365-day convention, interest is $245,000 × 12% × 20 ÷ 365 = $1,610.96. The estimated net saving is $5,000 − $1,610.96 − $250 = $3,139.04.
This example assumes the normal-payment alternative needs no borrowing and cash available on day 30 can repay the draw and charges. It excludes taxes and assumes the discount applies to the entire stated invoice. Actual interest conventions, minimum charges, tax treatment and eligible invoice amounts must come from the relevant agreements.
Test the collection delay that could erase the saving
Now suppose the same business cannot repay until day 70, so the early-payment draw lasts 60 days. Interest becomes $4,832.88. With the $250 fee, total cost is $5,082.88, exceeding the discount by $82.88. Against a no-borrowing alternative, the saving has disappeared.
However, if paying normally would also require borrowing from day 30 to day 70, charging all 60 days solely to the discount would be misleading. Model that second draw, its larger principal and its fees too. Compare the difference between the two scenarios. The practical lesson is to identify the repayment source and compare like-for-like alternatives, rather than treating an invoice due date as a repayment promise.
Protect the cash buffer before choosing a payment date
A positive net saving is one decision test, not the whole decision. Write down the minimum cash needed for payroll, taxes, critical suppliers and scheduled debt payments through the next collection cycle. Then test a delayed customer payment and a lower-than-expected receipt. Available credit should be checked under current draw conditions, not inferred from a headline facility limit.
For example, if paying $245,000 early leaves only $35,000 of unrestricted cash but $80,000 of essential payments fall due before reliable receipts, the business has a $45,000 liquidity shortfall unless other usable funds are confirmed. Do not count an undrawn amount twice as both financing for the invoice and the emergency buffer.
A supplier-discount decision checklist
- Verify the eligible invoice balance, discount percentage, deadline and payment-receipt requirements in writing. Resolve disputed quantities or credit notes before calculating the saving.
- Prepare both payment schedules, including the expected repayment date and a delayed-collection case. Show the source of cash used to repay each draw.
- Obtain the actual interest calculation, draw charges, minimum interest, repayment charges and other incremental costs. Include setup costs if a new facility is necessary.
- Check permitted uses, available drawing capacity and any conditions that could prevent access before the supplier deadline. Do not commit on the assumption of approval.
- Set a minimum operating cash buffer and show the lowest cash balance under each alternative. Include existing borrowing and upcoming compulsory payments.
- Assign someone to confirm receipt of payment and application of the discount. Reconcile the supplier statement and record the realized saving after borrowing costs.
Separate a recurring funding need from a one-off discount
Repeated supplier discounts may justify evaluating an operating facility, but one profitable calculation does not establish affordability for an entire year. Plot overlapping invoices, customer collections and outstanding draws. A series of individually attractive purchases can create a persistent balance that the business cannot clear. Do not multiply one saving by every invoice unless the same terms and funding capacity actually apply.
For context on facility structures and preparation, read our working capital financing guide: https://www.creativeglobalfundingservices.com/working-capital-financing-options-terms/
Supplier discount FAQs
Should I always take a discount if it exceeds the interest rate?
No. A discount applies to an invoice over a particular period, while a quoted interest rate usually covers a year. Compare dollar costs over the relevant dates, include fees and preserve operating liquidity.
Is an early-payment discount the same as supplier financing?
The discount rewards earlier payment; normal trade credit allows payment later under the supplier agreement. Borrowing from a separate capital provider to pay early introduces its own costs and obligations.
What if funding is not ready before the discount expires?
Do not assume the supplier will extend it. Ask for revised written terms and rerun the comparison. A potential discount should not become a commitment to financing that is unavailable or unsuitable.
Prepare a business funding discussion
CGFS connects qualified businesses and project owners with potential capital providers and reviews requests of USD $1 million or more. For a broader operating-capital need, bring your invoice schedule, cash forecast, existing debt and proposed repayment source. The smaller transaction example above is educational and does not establish a CGFS offering or minimum exception. Contact CGFS: https://www.creativeglobalfundingservices.com/contact.php
Funding is subject to independent review, due diligence, acceptable terms and final approval. This article is general funding education, not an offer or a guarantee. Featured image: original AI-generated conceptual illustration; it does not depict a CGFS client or financed business.
More Funding Insights
Inventory Financing: Why Stock Value May Not Become Available Credit
A warehouse full of stock does not establish borrowing availability. Prepare an inventory eligibility report and test how exclusions affect your funding plan.
Read insight →
Accounts Receivable Aging: Prepare a Clear Business Funding Review
Prepare an accounts receivable aging report for a funding discussion. Review overdue invoices, customer concentration and collection timing with a worked example.
Read insight →
Cash Timing Worksheet: Explain Receipts, Payments and a Funding Gap
Build a weekly cash timing worksheet that shows when receipts arrive, when payments fall due and where funding is needed. Includes a worked example and checklist.
Read insight →