Business Funding Conversation: What Should You Ask Before Moving Forward?
Preparing for a business funding conversation? Use this practical agenda to clarify fit, required evidence, costs, decision status and the next step before moving forward.
Before moving forward after a business funding conversation, ask five things: does the opportunity fit, what evidence is needed, what costs and obligations could apply, who makes the decision, and what happens next? Leave with a written list of open questions and responsibilities. A productive first call establishes whether further review makes sense; it does not establish that money will be available.
For business owners and project developers, the most useful preparation is a short agenda tied to the decision you need to make. This guide provides an original planning framework for that conversation, rather than a promise that any particular lender will accept your proposal.
Start with the decision, not just the dollar amount
Write one sentence explaining the opportunity, the requested amount and currency, the use of funds, and the date by which a decision matters. Then identify what is already supported by documents and what remains an estimate. A purchase deadline, equipment delivery date or permit dependency should be described accurately, with its source and any flexibility.
For example: “We are evaluating an expansion with a preliminary USD 3 million budget, including USD 750,000 of proposed owner funds. We want to understand whether the remaining requirement merits further review before committing to a premises agreement.” This is an illustrative scenario, not an available financing structure or a recommended contribution ratio.
1. Does this opportunity fit the review criteria?
Ask which features matter at the initial screening stage: location, industry, operating history, transaction size, business cash flow, asset type or project stage. Ask whether the proposed use of proceeds creates a limitation and whether a different structure would require a different review. The answer may be “not enough information yet.” That is useful if the missing information is identified.
Eligibility is specific to the capital source and program. For example, the U.S. Small Business Administration states that lenders and loan programs have their own requirements and that repayment ability and a sound business purpose are relevant to SBA eligibility. That is a U.S. program example, not a statement that CGFS offers SBA products or that SBA criteria apply internationally. Source: https://www.sba.gov/loans/
2. What evidence is needed for the next decision?
Ask for the smallest useful document set for the stated stage, the reporting periods required and the acceptable format. Distinguish an introductory discussion from formal underwriting. A historical financial statement, current interim report and forecast describe different periods and should not be presented interchangeably. Label forecasts and explain their assumptions.
Useful questions include: Which figures need reconciliation? Does the budget include all project costs? What evidence supports the proposed owner contribution? Which existing obligations need to be disclosed? Who should resolve a mismatch between the summary and the underlying records? Agree on an appropriate document-sharing method before sending confidential files.
3. What would the proposed structure actually require?
Ask about costs and obligations as questions, without assuming that terms have been offered. For debt, request clarification of the rate basis, payment timing, maturity, fees, security, guarantees, financial reporting and any restrictions. If interest is variable, ask how changes would affect payments. If repayment depends on a refinancing or sale, identify the assumptions and what happens if that event is delayed.
For an equity discussion, ask how ownership, decision rights, distributions and exit expectations would be assessed. A headline amount alone does not answer these questions. Before accepting documents or making commitments, have the relevant legal, accounting or other adviser review the proposed obligations.
Clarify who receives each proposed fee, what service it covers, when it becomes payable and whether it is refundable. Ask which items remain estimates. Keep a record of the answer and compare it with the written terms; resolve discrepancies before proceeding. Do not treat a quoted amount as cash available to spend until deductions, reserves, conditions and disbursement arrangements are understood.
4. Who decides, and what does the current status mean?
Ask the person you are speaking with to explain their role and identify who makes the lending or investment decision. Ask whether the discussion reflects preliminary interest, an indicative proposal, a conditional approval or a later stage. These labels should be clarified in the actual documents, including any conditions, expiry dates and further approvals.
CGFS explains that capital providers make independent decisions and that indicative terms or fee payments do not guarantee funding. Its published process describes preliminary review, underwriting and closing as distinct stages. Review the process before the call so you can ask about the stage relevant to your request: https://www.creativeglobalfundingservices.com/cgfs-funding-process/
5. What is the next step, and who owns it?
End the discussion with an agreed action, responsible person and target date. Separate a target from a commitment. If timing depends on a valuation, permit, document review or third-party response, record the dependency rather than simply writing “funding next month.” Ask what could prevent progress and how a changed fact should be reported.
In the illustrative expansion scenario, a useful outcome might be: the owner will provide the cost breakdown and recent financial reports; the reviewer will identify remaining screening questions after receipt; the premises commitment remains undecided. That outcome gives the business a concrete next step without implying approval, pricing or a closing date.
A checklist to bring to your capital conversation
- A one-sentence description of the business or project and the decision you need to make.
- Requested amount and currency, intended uses and a clearly labelled preliminary budget.
- A summary of existing funding, proposed contributions and unresolved funding gaps.
- Current supporting facts, document dates and a separate list of assumptions or missing evidence.
- Your five priority questions about fit, evidence, obligations, decision status and next steps.
- Space to record answers, unresolved issues, responsible people and target dates.
Frequently asked questions
Should I bring a complete application to the first call?
Ask what the recipient needs for that stage. Prepare enough reliable information to explain the opportunity and support the key numbers, but do not assume that every document is required immediately. Confirm the requested scope and secure delivery method.
Does a positive conversation mean the financing is approved?
No. Ask what has actually been decided, who has authority to decide and which conditions remain. Preserve the written explanation. Avoid committing expenditure based solely on encouraging language during an introductory call.
What if I cannot answer a question?
Say what is unknown and agree how to establish it. A dated estimate with explicit assumptions is more useful than a confident unsupported number. Correct inaccurate information promptly and explain which other figures or decisions it affects.
Bring your opportunity into focus with CGFS
CGFS reviews business and project financing inquiries of USD 1 million or more. Prepare a clear description, funding need and supporting facts for an initial assessment. An inquiry is not a commitment to lend, invest or arrange financing; opportunities remain subject to review, due diligence, underwriting and final approval. Start here: https://www.creativeglobalfundingservices.com/request-funding.php
Featured image: original AI-generated conceptual campaign illustration. The buildings are illustrative and do not depict a CGFS client or a financed property.
More Funding Insights
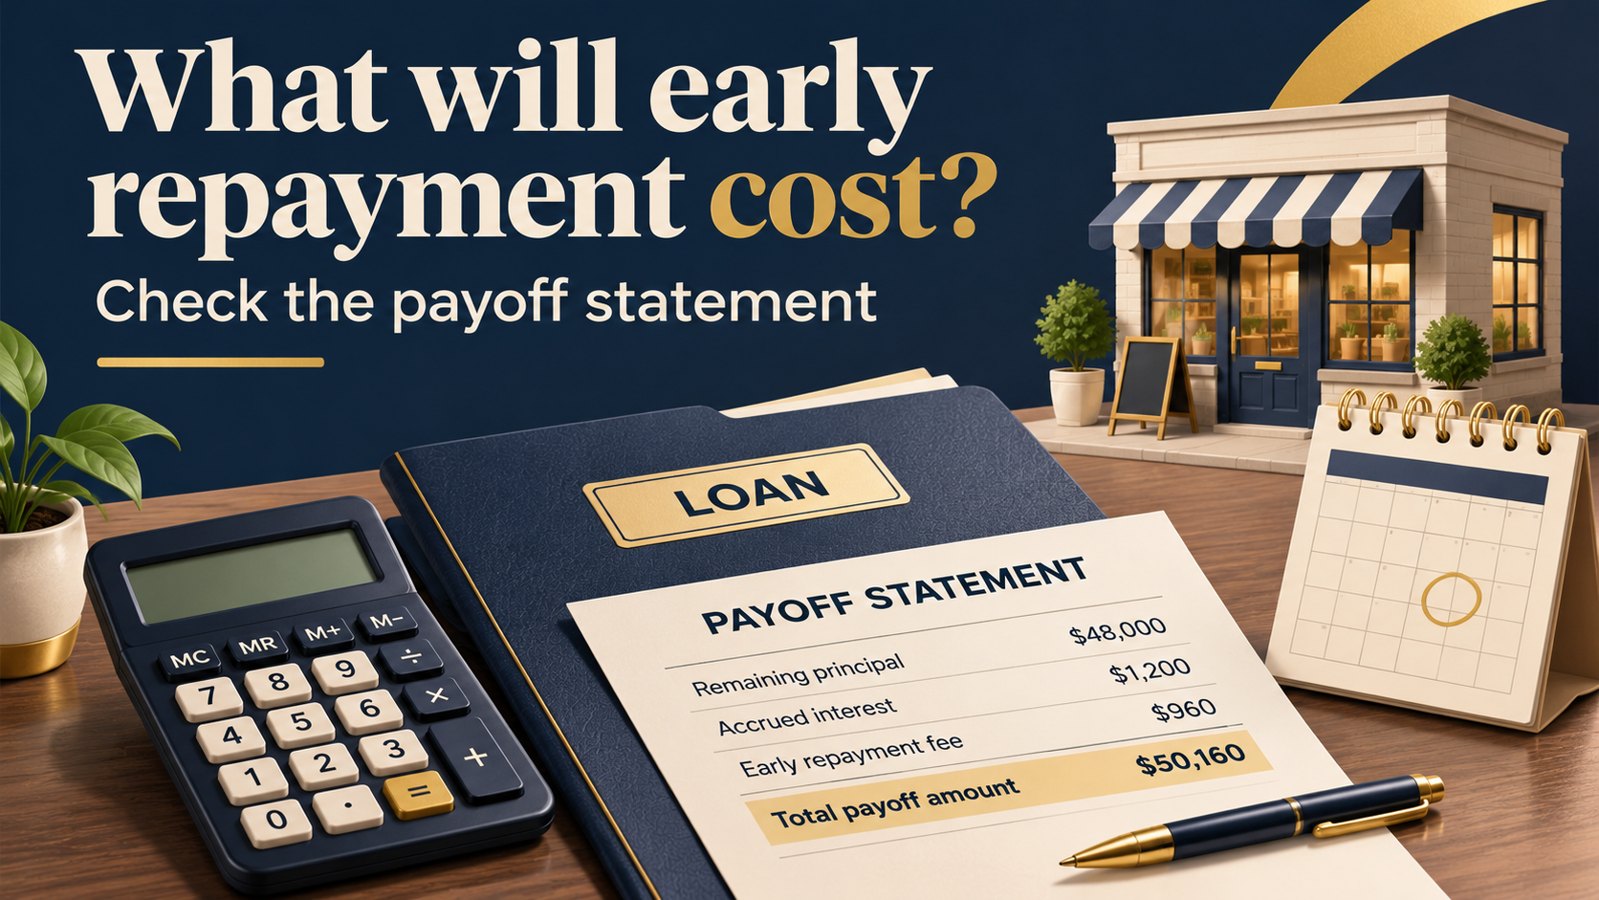
Business Loan Early Repayment: What Will the Payoff Cost?
Repaying a business loan early? Reconcile principal, accrued interest and agreed charges before committing cash. Includes a payoff example and preparation checklist.
Read insight →
Net Loan Proceeds: How Much Cash Will Be Available at Closing?
Does the stated loan amount cover your immediate needs? Reconcile the closing advance, fees, payoffs and reserves to find the cash actually available.
Read insight →
Funding Due Diligence Tracker: What Is Still Outstanding?
Stop losing funding due diligence questions in email. Track each request, document version, response and reviewer confirmation with a practical register.
Read insight →