Business Loan Early Repayment: What Will the Payoff Cost?
Repaying a business loan early? Reconcile principal, accrued interest and agreed charges before committing cash. Includes a payoff example and preparation checklist.
Business loan early repayment can require more cash than the outstanding principal shown on your latest statement. Before committing to a payoff or refinancing, obtain an itemized quote for the intended settlement date, check the agreement’s prepayment conditions, and reconcile the total against money actually available. Then test what cash remains for operations. The useful question is not simply whether the loan can be repaid early, but what that decision costs on a specific date.
Start with the agreement and a dated payoff quote
BDC explains that early repayment options depend on the particular product and loan agreement. Its guidance is a reminder to read your own terms, not evidence of a universal prepayment privilege or a CGFS product feature. Source: https://www.bdc.ca/en/financing/financing-faq
Ask the lender or servicer for a statement that identifies principal, accrued interest, any contractual prepayment charge, other applicable costs and credits. Confirm the date through which it is valid and what happens if settlement moves. Identify any notice requirement, permitted payment window or restriction before setting a completion date. Have your legal or accounting adviser explain unclear provisions rather than estimating their effect from another borrower’s loan.
Understand the amounts on the statement
Principal is the unpaid amount borrowed. Accrued interest is interest earned by the lender but not yet paid through the relevant date. A prepayment charge or indemnity, where applicable, is a separate amount associated with repayment ahead of schedule. Administrative or release costs may also appear if supported by the applicable arrangements. Do not assume every loan includes every charge.
Reconcile each line to its basis and avoid adding a charge twice. For example, if interest through the payoff date is already included, do not add the same period again from an old monthly statement. Ask how a scheduled installment falling before settlement will be credited. A quote prepared before that installment may need updating after it posts.
Illustration: principal is not the full payoff
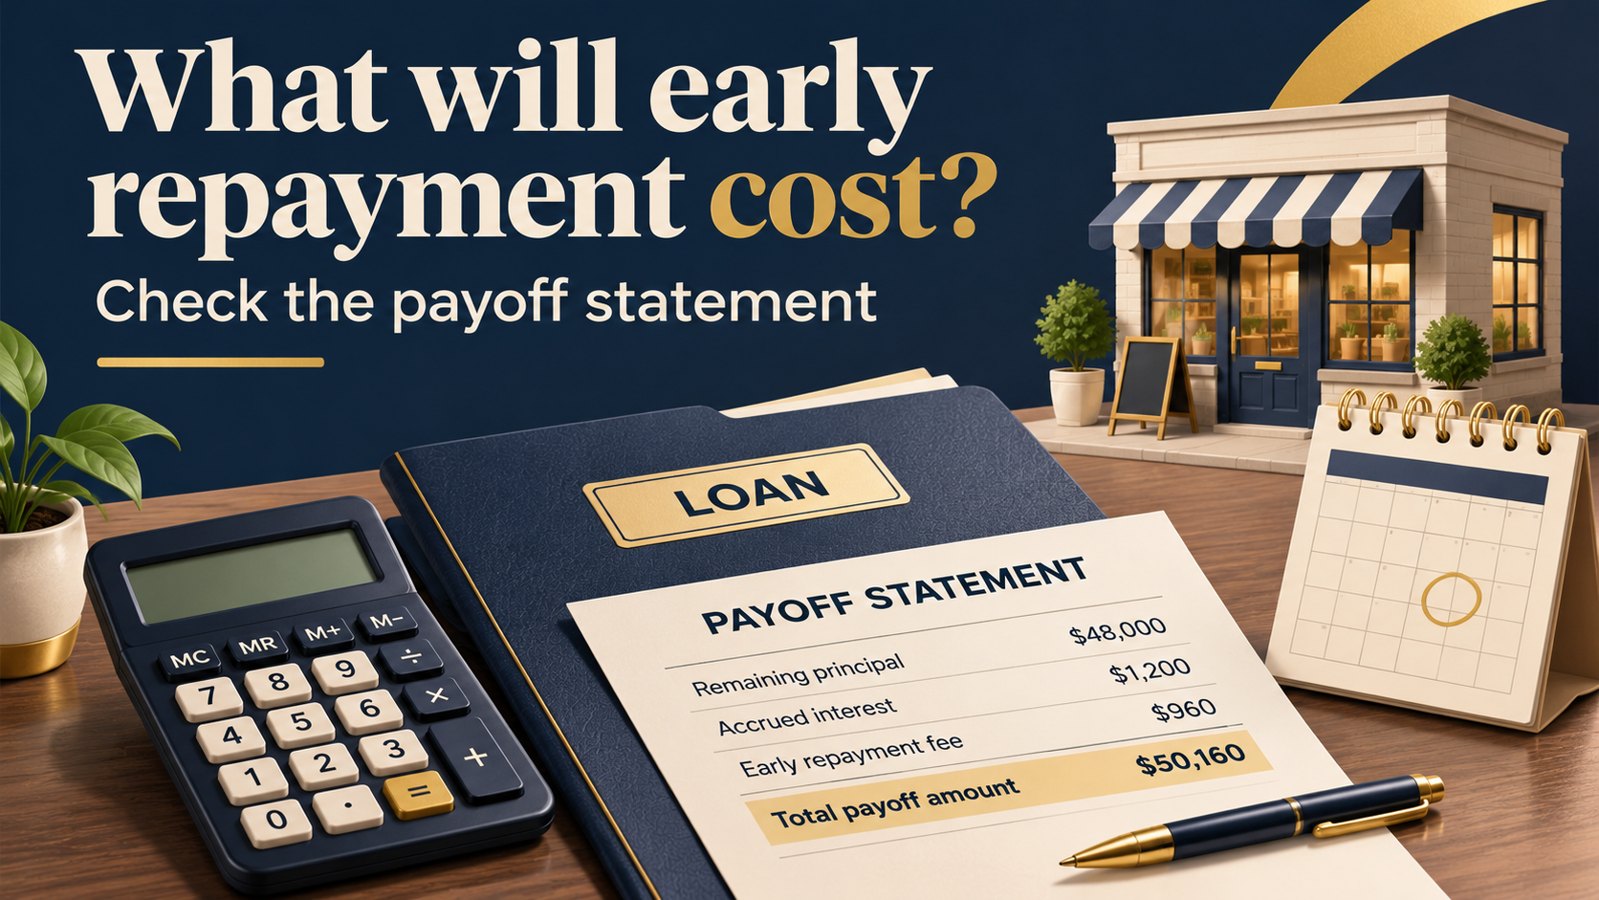
The featured image uses a fictional teaching example: $48,000 of remaining principal, $1,200 of accrued interest and a $960 early repayment fee total $50,160. These figures are illustrative, not typical charges, a lender quote or a CGFS funding offer. The same reconciliation method applies to larger transactions.
Consider a separate fictional business refinancing in USD. Assume principal of $1,200,000, accrued interest of $8,000, an agreed prepayment charge of $24,000 and $3,000 of other settlement costs. Total uses to clear the old loan are $1,235,000. Assume no other charges or credits. Proposed new loan proceeds of $1,250,000 less $30,000 of deductions leave $1,220,000 available. The borrower must therefore identify another $15,000 to complete the payoff.
If the business also needs to retain $100,000 of operating cash and has $110,000 of unrestricted cash before contributing to settlement, using $15,000 leaves only $95,000. The closing can be funded, but the operating cash target is missed by $5,000. Resolve that separate gap instead of treating a balanced closing as proof of adequate liquidity. The reserve here is an assumed planning target, not a lender requirement.
Compare refinancing over the same horizon
A smaller monthly payment does not by itself establish a lower total cost. Compare the current and proposed schedules through the same date, including fees and the remaining balance at that date. Extending repayment may reduce near-term payments while leaving more debt outstanding. Distinguish principal repayment from financing cost when presenting the comparison.
Build two columns: keep the existing loan, and refinance on the proposed date. List dated cash payments, upfront charges and the outstanding debt at the end of the comparison period. Use the same assumptions for operating performance. Ask an adviser to review tax effects and any present-value comparison where those are material. An initial interest-saving estimate should not be presented as guaranteed savings.
For the new facility, verify net proceeds, conditions and permitted uses. A stated loan amount may include deductions or money restricted to another purpose. Our net loan proceeds guide explains the closing-cash distinction: https://www.creativeglobalfundingservices.com/net-loan-proceeds-cash-at-closing/
Plan for a changed settlement date
Give one person responsibility for keeping the payoff quote and funding schedule aligned. If a closing slips, request a revised quote or written instructions for calculating the revised amount. Confirm receipt deadlines, how the payment is applied and the evidence that the balance has been discharged. Coordinate any required security release with the professionals handling the transaction.
Treat partial prepayment as a separate question. Ask whether it reduces future installments, shortens repayment, or has another effect under the agreement. Do not assume that paying extra principal automatically reduces next month’s payment. Also establish whether a permission for partial repayment applies to a complete payoff; the two can have different conditions.
Early repayment preparation checklist
- Read the prepayment clause, notice requirement and any applicable permission or restriction.
- Request an itemized payoff statement for the intended settlement date.
- Reconcile principal, interest, charges, credits and pending installments without duplication.
- Confirm new funding net proceeds, availability date and permitted uses if refinancing.
- Test remaining operating liquidity and compare both debt schedules over the same horizon.
- Assign responsibility for updated quotes, settlement evidence and required releases.
Frequently asked questions
Does every business loan have a prepayment penalty?
No universal answer applies. Check the specific agreement and ask for the written calculation where a charge applies. Product descriptions from another lender do not establish the terms of your facility.
Can I use the balance on my monthly statement as the payoff amount?
Use a current dated payoff quote. A statement balance may not include all interest through the payment date, contractual charges or subsequent credits. Reconcile the differences before transferring funds.
Should I repay early whenever I have spare cash?
Compare the supported cost savings with charges and the cash needed for payroll, suppliers, taxes, contingencies and planned investment. Cash that appears surplus today may already be needed for later obligations. Review the decision with advisers using a dated forecast.
Prepare a clear funding discussion
Creative Global Funding Services reviews business and project financing requests of USD $1,000,000 or more. If a proposed funding request includes refinancing, provide the current debt schedule, payoff information, proposed use of funds and operating cash forecast. Identify estimates and unresolved conditions. Start an initial inquiry: https://www.creativeglobalfundingservices.com/request-funding.php
Submitting an inquiry is not a commitment to lend, invest or arrange financing. Opportunities remain subject to review, due diligence, underwriting and final approval. This is general funding education, not transaction-specific legal or tax advice. The original AI-generated featured image is conceptual; its shop and payoff figures do not represent a real CGFS client, financed business or quoted terms.
More Funding Insights
Business Funding Conversation: What Should You Ask Before Moving Forward?
Preparing for a business funding conversation? Use this practical agenda to clarify fit, required evidence, costs, decision status and the next step before moving forward.
Read insight →
Net Loan Proceeds: How Much Cash Will Be Available at Closing?
Does the stated loan amount cover your immediate needs? Reconcile the closing advance, fees, payoffs and reserves to find the cash actually available.
Read insight →
Funding Due Diligence Tracker: What Is Still Outstanding?
Stop losing funding due diligence questions in email. Track each request, document version, response and reviewer confirmation with a practical register.
Read insight →